
Advertisement
Did you know that nearly 60% of Americans struggle to manage their finances effectively? The 50/30/20 budgeting method offers a straightforward approach to help you take control of your money. This popular framework divides your after-tax income into three essential categories: needs, wants, and savings.
By allocating 50% of your income to needs, 30% to wants, and 20% to savings, you create a simple plan that balances essential expenses with lifestyle choices. This method is appealing because it doesn’t require tracking every single purchase, making it accessible for beginners.
Moreover, the percentages are flexible guidelines, which can be adjusted based on your unique circumstances, such as housing costs or financial goals. The aim is to ensure you can enjoy life while still preparing for the future.
In this article, we will guide you through calculating your after-tax income, classifying your expenses, and tracking your progress. With practical tips, you’ll be ready to implement this effective budgeting strategy in no time!
Understanding the 50/30/20 Budget Rule
Financial management can be a daunting task for many individuals. The 50/30/20 method simplifies this process by dividing your net income into three main categories. This approach focuses on what you actually have after taxes and deductions, making it a practical tool for effective budgeting.
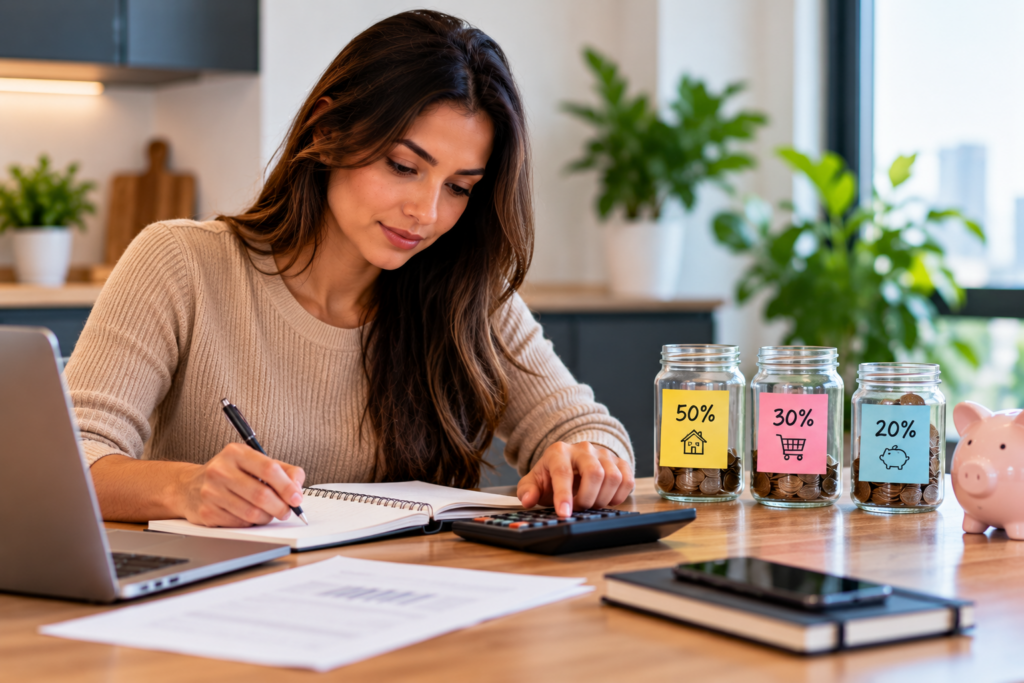
The 50/30/20 rule allocates 50% of your income to essential needs, 30% to nonessential wants, and 20% to savings or debt repayment beyond minimum payments. This clear division helps you understand your spending patterns without the need to track every transaction in detail.
Here’s why this method is popular among beginners:
- It’s easy to remember and quick to calculate.
- It offers flexibility, allowing you to adjust based on your unique financial situation.
- It encourages awareness of your spending habits, which can lead to better financial decisions.
By categorizing your expenses, you can identify how your lifestyle choices impact your financial progress. For instance, you might discover that your wants category is taking up too much of your income, affecting your ability to save. This awareness is key to achieving your financial goals.
Remember, the percentages are guidelines, not strict rules. You can start with a version that feels realistic for you and gradually refine your allocations over time. This flexibility is what makes the 50/30/20 approach a great starting point for anyone looking to take control of their finances.
| Category | Percentage | Description |
|---|---|---|
| Needs | 50% | Essential expenses like housing, food, and healthcare. |
| Wants | 30% | Nonessential items such as entertainment and dining out. |
| Savings | 20% | Funds for savings, investments, or debt repayment beyond minimums. |
The 50% Needs Category: Covering Your Essentials
Understanding the difference between needs and wants is crucial for effective financial planning. This distinction helps you prioritize your spending and ensure that your essential expenses are covered. Needs are the costs required to maintain basic living standards and meet financial obligations.
Defining Needs vs. Wants
A need is an expense necessary for keeping a household functioning or fulfilling a financial obligation. In contrast, a want is something that can usually be postponed or reduced. This distinction is vital for effective budgeting.
Common Examples of Needs
Common needs include:
- Housing (rent or mortgage)
- Utilities (electricity, water, gas)
- Groceries (basic food items)
- Transportation (public transit or car payments)
- Insurance (health, auto, and home)
- Childcare costs
- Minimum payments on loans and credit cards
It’s important to note that while minimum payments on loans belong in the needs category, any extra payments should be allocated to savings or debt repayment.
How to Manage High Essential Expenses
If your essential costs exceed 50% of your income, consider reviewing your expenses. Here are some strategies:
- Compare insurance rates to find better deals.
- Look for ways to reduce transportation costs, like carpooling or using public transit.
- Choose a less expensive phone plan.
- Evaluate your housing options for potential savings.
- Temporarily reduce spending in the wants category.
Asking yourself, “Could I reasonably postpone or live without this purchase this month?” can also guide your decisions.
| Essential Needs | Examples | Potential Adjustments |
|---|---|---|
| Housing | Rent or mortgage payments | Consider downsizing or refinancing |
| Utilities | Electricity, water, gas | Implement energy-saving measures |
| Groceries | Basic food items | Plan meals and use coupons |
| Transportation | Car payments, public transit | Use carpooling or public transport |
| Insurance | Health, auto, home | Shop around for better rates |
The 30% Wants Category: Enjoying Your Lifestyle Responsibly
Finding a balance between enjoying life and managing finances can be challenging. The wants category is where you can allocate a portion of your income to experiences and items that enhance your lifestyle. These are the expenses that improve comfort, convenience, or enjoyment but are not essential for basic living.
What Counts as Wants?
Wants can include a variety of lifestyle purchases. Think of dining out, entertainment options, streaming services, and hobbies. Other examples are vacations, upgraded electronics, nonessential clothing, and gym memberships. These expenses allow you to enjoy life, but they should be carefully considered within your financial plan.
Balancing Fun and Financial Responsibility
Including wants in your budget is not irresponsible. In fact, doing so can make your financial plan more sustainable over time. When you allocate 30% of your income to this category, you can enjoy life while still being mindful of your financial goals. The key is to prioritize what brings you the most satisfaction.
How to Prioritize and Cut Back When Necessary
To make the most of your wants category, consider ranking your purchases by value. Focus on keeping the experiences and items that truly enhance your life. If you find your spending is too high, here are some practical ways to cut back:
- Cancel unused subscriptions to streaming services.
- Cook at home more often instead of dining out.
- Delay upgrades on electronics or clothing.
- Set limits on entertainment spending.
- Choose lower-cost alternatives for hobbies.
By implementing these strategies, you can enjoy your lifestyle while maintaining a healthy financial outlook. Remember, it’s all about finding the right balance!
The 20% Savings Category: Securing Your Financial Future
Saving money is not just about putting away cash; it’s about securing your future. The savings category plays a crucial role in your financial health. This portion of your income should be directed toward building a solid foundation for your financial goals. It encompasses emergency funds, debt repayment beyond minimums, and contributions to retirement accounts.
Prioritizing your savings can lead to long-term stability. A recommended order of focus includes:
- Building an emergency fund
- Paying down high-interest debt
- Contributing to retirement accounts
- Saving for specific goals, like a home
- Investing for long-term growth
Building an Emergency Fund
An emergency fund is essential for financial security. It should ideally cover at least three months of essential expenses. Starting small is perfectly fine; any amount you save can provide peace of mind. This fund acts as a financial cushion during unexpected situations, like job loss or medical emergencies.
Debt Repayment Beyond Minimums
Understanding the difference between minimum debt payments and extra payments is vital. Minimum payments belong in the needs category, while additional payments toward credit cards, car loans, or student loans can count toward your savings. Prioritizing these extra payments can help reduce your overall debt faster, saving you money on interest in the long run.
Saving for Retirement and Other Long-Term Goals
Retirement savings should be a key component of your financial plan. Options include employer-sponsored 401(k) plans, which often provide matching contributions, and Individual Retirement Accounts (IRAs). These accounts allow your money to grow over time, benefiting from compound interest.
Encouraging automatic transfers to your savings and debt payments can help ensure consistency. By setting these transfers before discretionary spending, you prioritize your financial future.
| Saving Focus | Description | Recommended Amount |
|---|---|---|
| Emergency Fund | Funds set aside for unexpected expenses | 3-6 months of essential expenses |
| Debt Repayment | Payments beyond minimums to reduce debt faster | As much as possible after needs |
| Retirement Savings | Contributions to retirement accounts | At least 10-15% of income |
| Specific Goals | Savings for future purchases like a home | Variable based on individual goals |
| Investments | Long-term investments for wealth growth | Based on risk tolerance |
How to Apply the 50/30/20 Budget Rule in Real Life
Many people find themselves unsure of how to implement a budgeting strategy in their daily lives. Applying the 50/30/20 method involves a few straightforward steps that can make a significant difference in managing your finances effectively.
Calculating Your Monthly After-Tax Income
Start by determining your monthly net income after taxes and deductions. This figure is crucial for establishing your budget. For those who receive weekly pay, multiply your typical paycheck by four for a basic estimate. If you are paid biweekly, use two paychecks to get a simple monthly estimate. Alternatively, you can calculate your annual net pay and divide it by twelve for greater accuracy.
Assigning Dollar Amounts to Each Category
Once you have your monthly net income, it’s time to assign dollar amounts to each category. For example, if your take-home income is $4,000, you would allocate:
- $2,000 for needs
- $1,200 for wants
- $800 for savings or extra debt repayment
If your monthly net income is $3,000, your targets would adjust to:
- $1,500 for needs
- $900 for wants
- $600 for savings or extra debt repayment
Adjusting Your Budget Based on Actual Expenses
After assigning amounts, review your bank and credit card statements over several months. This helps identify your actual spending patterns. Look for recurring, irregular, and discretionary costs. Comparing your target amounts with actual expenses is essential for refining your budget.
Example Budget Breakdown
For clarity, here’s an example breakdown using a monthly net income of $4,000:
| Category | Target Amount |
|---|---|
| Needs | $2,000 |
| Wants | $1,200 |
| Savings | $800 |
Additionally, for annual costs like car registration or holiday gifts, consider setting up a sinking fund. Divide the expected yearly amount by twelve and save that monthly amount. This approach helps manage larger expenses without impacting your budget significantly.
Remember, your first budget is just a starting point. Adjust it after observing your actual spending. It’s perfectly normal not to achieve perfect percentages immediately. The goal is to create a flexible plan that aligns with your financial goals.
Tools and Strategies to Track Your 50/30/20 Budget
Tracking your finances can be a game-changer in achieving your financial goals. Utilizing the right tools and strategies helps you stay on top of your budgeting and ensures you are aware of your spending habits. Here are some effective methods to consider.
Using Budgeting Apps and Bank Tools
Many budgeting apps and bank dashboards can automatically categorize your transactions into needs, wants, and savings categories. These tools provide a clear overview of your financial situation and progress toward your spending limits.
- Apps like Mint and YNAB (You Need A Budget) can simplify tracking.
- Bank tools often include features for tracking expenses and setting financial goals.
- Some apps allow you to set alerts for when you approach your category limits.
Benefits of Manual Tracking vs. Automation
Manual tracking can increase your awareness of spending decisions, as you actively record each purchase. This practice can help you understand your financial habits better. On the other hand, automation saves time and ensures consistency in tracking.
- Manual tracking promotes mindfulness about your financial choices.
- Automated tools can send alerts for low balances or upcoming bills.
Regular Review and Adjustments
It’s essential to review your budget regularly. Experts recommend checking in at least quarterly or whenever your income or major expenses change. Regular reviews help you stay aligned with your financial goals.
- Conduct quick weekly checks to monitor your spending.
- Perform detailed monthly reviews to adjust your financial plan as needed.
- Make comprehensive adjustments quarterly, especially after significant life changes.
Benefits and Limitations of the 50/30/20 Budget Rule
Navigating personal finances can be both rewarding and challenging for many individuals. The 50/30/20 budgeting method offers distinct advantages and some limitations. Understanding these aspects can help you make informed decisions about your financial journey.
Key Advantages for Beginners and Simple Finances
This budgeting approach is particularly beneficial for those just starting their financial journey. Here are some key advantages:
- Memorable Structure: The clear division into needs, wants, and savings makes it easy to remember.
- Flexibility: You can adjust the percentages based on your unique financial situation.
- Discretionary Spending: The 30% allocated for wants allows for reasonable lifestyle choices, making budgeting more sustainable.
- Easy Introduction to Saving: It encourages setting aside money for future goals, which is essential for financial health.
Common Challenges and When to Adapt the Rule
While the 50/30/20 method is effective, it does come with challenges:
- High Housing Costs: Many individuals find their essential expenses exceed 50% of their income.
- Irregular Income: Freelancers and gig workers may struggle with fluctuating income levels.
- Substantial Debt: High-interest debt can make it difficult to allocate funds effectively.
- Changing Childcare Expenses: Childcare costs can vary significantly, impacting budgeting.
- Medical Bills: Unexpected medical expenses can disrupt financial plans.
In such cases, consider adapting the percentages. For example, a 60/20/20 split can work better for high housing costs, while a 50/10/40 approach may suit those focusing on aggressive debt repayment.
Alternative Budgeting Approaches for Complex Needs
For those with more complex financial situations, alternative budgeting methods may be beneficial:
- Zero-Based Budgeting: Every dollar is assigned a specific purpose, making it a detailed approach.
- Debt Snowball Planning: Focus on paying off smaller debts first to build momentum.
- Pay-Yourself-First Budgeting: Prioritize savings before other expenses.
- 75/15/10 Model: This approach allows for 75% on needs, 15% on long-term savings, and 10% on short-term savings, with no dedicated wants category.
Ultimately, the goal is not to force exact percentages but to create a sustainable allocation that improves your financial decisions over time. By understanding the benefits and limitations of the 50/30/20 method, you can better tailor your approach to fit your life.
Conclusion
In conclusion, the 50/30/20 approach divides your after-tax income into needs, wants, and savings or debt repayment. This method serves as an excellent starting point for individuals with stable income and straightforward finances. However, it’s important to adapt your strategy as your income, expenses, and financial goals evolve.
To begin, gather accurate information from pay stubs, bank statements, and recurring bills. Take immediate action by tracking one month of spending or strengthening your emergency fund. Remember, paying off debt and building savings can happen gradually.
Ultimately, the percentages are flexible. A sustainable financial plan should reflect your unique income, housing costs, health needs, and family responsibilities. By doing so, you can create a budget that works for you and supports your financial well-being.